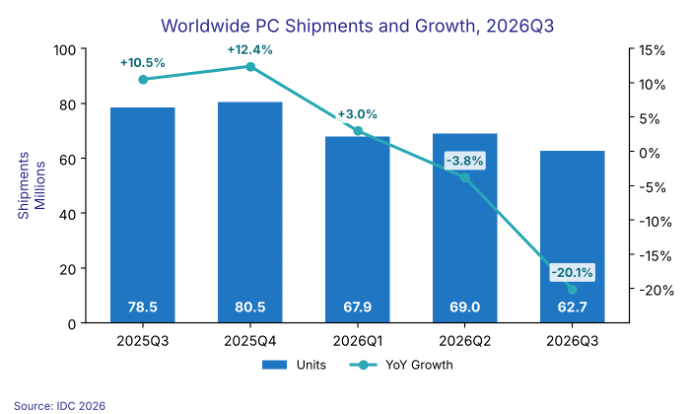
Worldwide personal computer (PC) shipments plunged 20.1% year-on-year to 62.7 million units in the third quarter of 2026, as rising component prices, supply constraints, and excess inventory weighed on the global market, according to preliminary data released by research firm IDC.
The decline marked the second consecutive quarter of falling PC shipments and was significantly steeper than the 3.8% contraction recorded in the second quarter.
Shipments also dropped 9.1% from the previous quarter, reversing the usual seasonal trend in which third-quarter shipments exceed those of the second quarter.
IDC attributed the downturn largely to manufacturers and distributors bringing forward their purchases earlier in the year to avoid anticipated price increases, particularly for memory components.
The inventory buildup during the first half of 2026 left distributors and retailers with substantial stocks, reducing demand for additional shipments during the third quarter.
The research firm also cited ongoing supply constraints and higher component prices associated with the expansion of artificial intelligence (AI) data centers as factors affecting the PC market.
“What we’re seeing is the result of the strong first half pull-in. Vendors and channels loaded up on inventory early in the year to get ahead of price hikes, and that has thrown off the usual seasonality, where Q3 is typically larger than Q2,” said Jitesh Ubrani, research director for consumer devices at IDC.
“Channels are now worried about carrying too much inventory into a market where high prices are suppressing demand. That could translate into promotions and some short-term relief for consumers, but we don’t expect pricing anywhere near what it was a year ago. Prices will remain elevated. With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better.”
Among the five largest PC manufacturers, HP recorded the steepest decline in shipments, falling 30.9% to 10.3 million units from 15 million units a year earlier. Its global market share slipped from 19.1% to 16.5%.
Lenovo retained its position as the world’s largest PC vendor, shipping 14.9 million units and capturing 23.8% of the market. However, its shipments declined 22.6% from 19.3 million units in the same quarter last year.
Dell Technologies ranked third with 7.6 million units shipped, down 25% year-on-year, giving it a 12.1% market share.
Apple placed fourth with 5.9 million units, representing an 11.3% decline. Despite the drop, its market share increased from 8.5% to 9.5%.
Asus ranked fifth with 5.5 million units shipped, down 8.6% from the previous year. Its market share rose from 7.6% to 8.7%.
The three largest vendors — Lenovo, HP, and Dell — all experienced shipment declines exceeding the overall market contraction, collectively losing 4.2 percentage points of market share.
IDC said retailers and distributors could introduce promotions to reduce their inventory, potentially providing temporary price relief to consumers.
However, the research firm expects PC prices to remain substantially higher than year-ago levels because of persistent supply constraints and elevated component costs.
It also warned that deteriorating economic conditions could further weaken demand during the remaining months of 2026 and into 2027.
The IDC figures cover traditional PCs, including desktops, notebooks, and workstations, but exclude tablets and x86 servers.
The research firm’s quarterly tracker monitors PC market developments across more than 90 countries.